When you need to borrow money for a major purchase, consolidate debt, or fund a life milestone, one of the most fundamental choices you will face is whether to apply for a secured loan or an unsecured loan.
The primary difference between the two financing structures comes down to risk and collateral. Lenders evaluate risk differently for secured and unsecured debt, which directly impacts your interest rates, borrowing limits, approval odds, and the legal consequences of default. This comprehensive guide breaks down how secured and unsecured loans work, compares their key features, and helps you determine which option aligns with your financial strategy.
What Is a Secured Loan
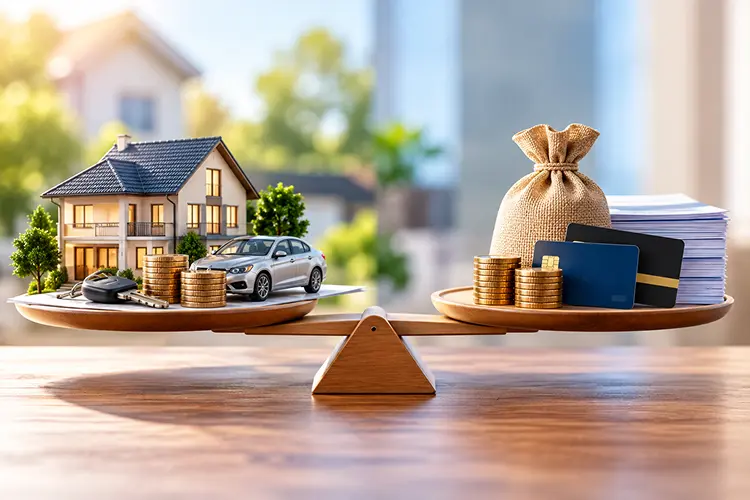
A secured loan is a borrowing arrangement that requires you to pledge an asset—known as collateral—as security for the debt. Common examples of collateral include residential or commercial real estate, automobiles, savings accounts, or certificates of deposit.
How It Works: By offering collateral, you give the lender legal claim to that asset if you fail to repay the loan according to the agreed-upon terms. Because the lender's risk is significantly reduced, they are typically willing to offer more favorable borrowing conditions.
Key Characteristics:
Lower Interest Rates: Because the debt is backed by tangible assets, lenders reward borrowers with substantially lower annual percentage rates.
Higher Borrowing Limits: Borrowers can often secure much larger sums of money for a mortgage or commercial property.
Stricter Qualification and Appraisal: Lenders require thorough documentation, credit checks, and professional appraisals of the collateral before issuing funds.
Prime Examples of Secured Loans
Mortgages: Your home serves as the collateral for the loan, and failure to pay leads to foreclosure.
Auto Loans: The vehicle you purchase acts as the collateral, allowing repossession upon default.
Secured Personal Loans: Backed by a cash deposit held in a savings account to build or rebuild credit.
What Is an Unsecured Loan
An unsecured loan does not require any form of collateral. Instead of seizing an asset if you fail to pay, the lender extends credit based solely on your creditworthiness, financial history, income verification, and promise to repay.
How It Works: Lenders take on significantly higher risk when issuing unsecured debt because they have no physical asset to repossess if you default. To offset this elevated risk, unsecured loans generally feature stricter credit score requirements, lower borrowing maximums, and higher interest rates.
Key Characteristics:
No Asset Risk: Your personal property, home, and vehicle are not directly tied to the agreement, meaning default will not result in immediate asset seizure.
Faster Approval Times: Because property appraisals and asset title searches are unnecessary, unsecured loans can often be approved and funded much faster.
Higher Interest Rates: Annual percentage rates are typically higher to compensate the lender for taking on unsecured risk.
Prime Examples of Unsecured Loans
Unsecured Personal Loans: Fixed-term loans used for debt consolidation, medical expenses, or home improvements without tying up property.
Credit Cards: Revolving lines of credit that allow you to make purchases up to a credit limit without pledging collateral.
Student Loans: Many federal and private student loans are issued without requiring collateral.
Key Differences Between Secured and Unsecured Loans
Collateral Requirement: Secured loans require physical or financial collateral to back the debt, whereas unsecured loans require zero collateral.
Interest Rates: Secured loans generally feature lower annual percentage rates due to reduced lender risk, while unsecured loans carry higher rates.
Borrowing Limits: Secured loans typically offer much higher borrowing capacities tied to asset value, whereas unsecured loans have lower maximum limits determined by income and credit.
Approval Criteria: Secured loans focus heavily on the value of the collateral alongside credit history, while unsecured loans rely almost entirely on credit scores and income stability.
Default Consequences: Defaulting on a secured loan results in the immediate seizure of your pledged asset, whereas defaulting on an unsecured loan severely damages your credit score and can result in collections or lawsuits.
How to Choose the Right Loan Type
Selecting between a secured or unsecured loan depends on your specific financial goals, risk tolerance, and available assets:
When to Choose Secured Financing: If you are making a major capital purchase like a home or reliable vehicle, secured financing is standard and allows you to access low interest rates.
When to Choose Unsecured Financing: If you need to cover an unexpected short-term expense or consolidate high-interest credit card debt without risking your home or vehicle, an unsecured personal loan is often the safer choice.
Evaluate Total Cost: Always compare the interest rates, origination fees, and repayment terms of both options before committing.