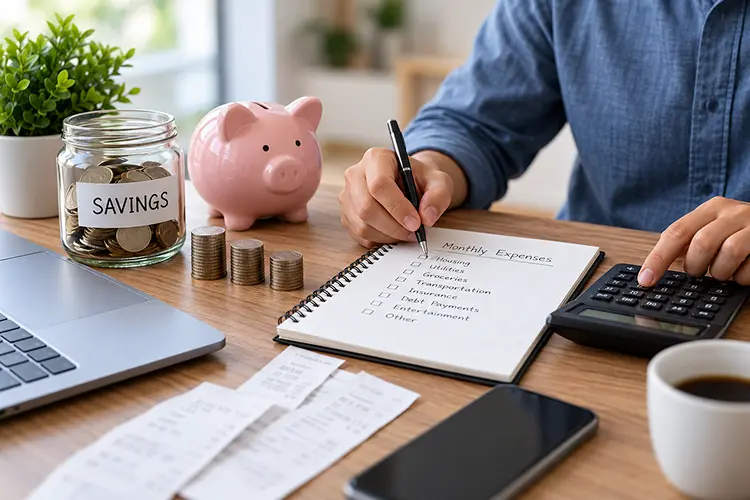
Managing monthly expenses is not about completely sacrificing comfort or eliminating the things that bring you joy; rather, it is about gaining clarity on your cash flow and making intentional choices. Over time, small recurring costs and unmonitored spending can quietly drain your bank account, making it difficult to build savings or achieve long-term financial goals.
Whether you are trying to free up cash for an emergency fund, pay down debt, or simply cushion your monthly budget, implementing practical cost-cutting strategies can make a dramatic difference. Here is a comprehensive guide on how to audit, manage, and successfully reduce your monthly expenses.
Step 1: Know Where Your Money Goes
Before you can cut expenses, you need a clear, unvarnished picture of your current spending habits. Many people receive their income, spend throughout the month, and wonder where it all vanished.
Track Every Dollar: For at least 30 to 60 days, review your bank statements, credit card bills, and digital payment history to log every single purchase.
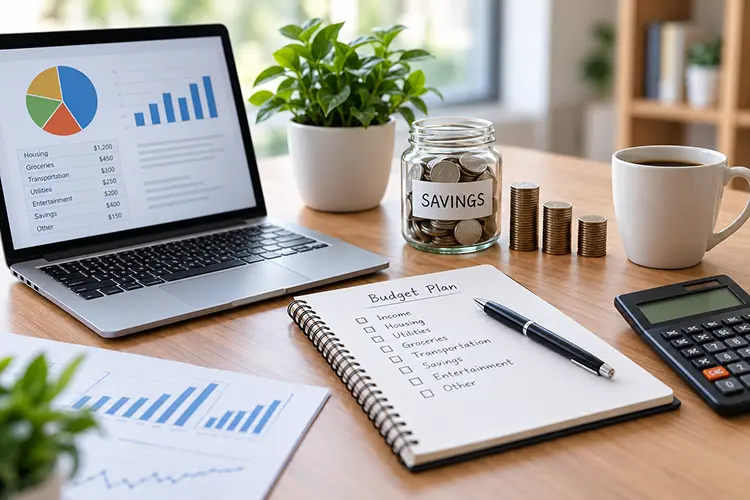
Categorize Your Spending: Group your expenses into clear categories such as housing, utilities, groceries, transportation, debt obligations, and discretionary entertainment.
Spot the Leaks: Tracking reveals hidden spending patterns such as frequent food delivery, unused digital subscriptions, or impulsive online shopping that can easily be trimmed.
Step 2: Audit and Trim Recurring Monthly Costs
Recurring monthly bills are among the easiest expenses to overlook because they often run on auto-pilot. However, recurring charges add up rapidly over the course of a year.
Cancel Unused Subscriptions: Review your statements for streaming services, digital apps, software plans, and gym memberships that you no longer actively use. If you subscribe to multiple entertainment platforms, consider rotating them based on what you are currently watching rather than keeping all of them active simultaneously.
Review Telecom and Utility Plans: Check your mobile phone and internet plans periodically. You might be paying for data limits or features far exceeding your actual usage.
Shop Around for Insurance: Insurance premiums can quietly creep upward over time. Compare quotes for auto, home, and renters insurance annually to ensure you are still getting the most competitive rate.
Step 3: Optimize Your Food and Grocery Spending
For most households, food represents one of the largest flexible monthly expenses, making it a prime target for immediate savings.
Plan Meals in Advance: Map out your weekly menu, create a strict grocery shopping list, and stick to it religiously to prevent impulse purchases.
Reduce Dining Out and Delivery: Frequent restaurant visits, takeout orders, and convenience fees from food delivery apps can dramatically inflate monthly food costs. Reserve dining out for intentional treats rather than weekday convenience.
Buy Store Brands and Shop Sales: Opt for generic or store-brand grocery items, buy non-perishable goods in bulk when appropriate, and check supermarket apps for weekly discounts on items you already buy.
Step 4: Streamline Transportation and Commuting Costs
Vehicle maintenance, fuel, and transit costs can place a heavy burden on monthly cash flow.
Consolidate Errands: Combine multiple short trips into a single outing to optimize fuel consumption and reduce wear and tear on your vehicle.
Explore Alternative Commuting: Consider carpooling with coworkers, utilizing public transit, or cycling when feasible to save on fuel and parking fees.
Maintain Your Vehicle: Regular oil changes, tire pressure checks, and routine servicing improve fuel efficiency and prevent expensive emergency repairs down the road.
Step 5: Embrace Mindful Spending Habits
Shifting your mindset toward everyday purchasing decisions helps lock in long-term financial health.
Implement a Cooling-Off Period: Before buying non-essential items, wait 24 to 48 hours. This brief delay helps eliminate impulse-driven purchases.
Distinguish Needs from Wants: Prioritize absolute necessities (housing, utilities, basic groceries) over luxury items and discretionary upgrades.
Automate Your Savings: Once you successfully cut expenses, immediately route the newly freed-up cash into a high-yield savings account or emergency fund so it doesn't get absorbed into lifestyle inflation.