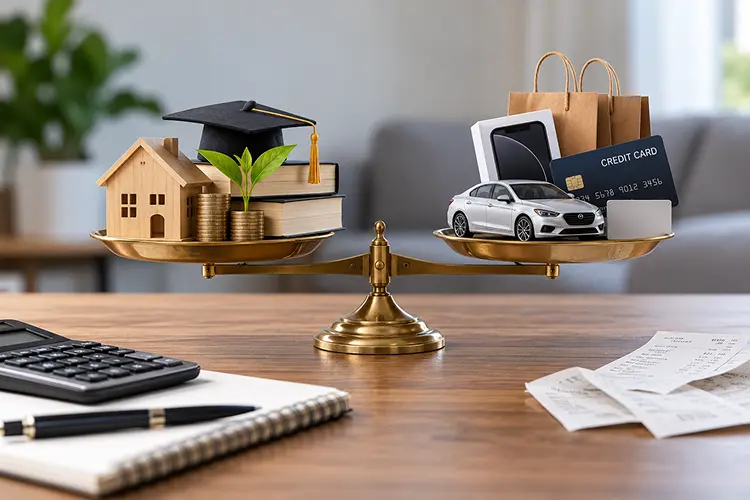
Debt is often viewed as a universal enemy of personal finance. Popular financial culture frequently preaches that all borrowing is inherently dangerous and that true financial freedom requires living entirely debt-free. However, a nuanced look at personal wealth reveals that not all debt is created equal.
Understanding the fundamental difference between good debt and bad debt is one of the most transformative skills you can develop. When utilized strategically, certain types of debt can accelerate wealth-building, expand your earning potential, and secure your financial future. Conversely, mismanaged debt can trap you in a compounding cycle of high-interest obligations. Here is how to distinguish between the two and leverage financing wisely.
What Defines "Good Debt"?
Good debt is broadly defined as borrowing money to finance assets that either appreciate in value over time or generate long-term income, ultimately improving your net worth. Rather than draining your resources, good debt acts as an investment tool that pays dividends or builds equity.
Characteristics of Good Debt:
Low Interest Rates: Typically carries favorable, predictable borrowing costs (often well below historical market investment returns).
Value Appreciation: Tied to an underlying asset that generally increases in value (e.g., real estate, commercial property).
Income Generation: May directly or indirectly increase your earning capacity or produce passive cash flow.
Prime Examples of Good Debt:
Mortgages for Primary Residences or Real Estate: Purchasing a home allows you to lock in housing costs and build equity over time through property appreciation and principal paydown, rather than paying rent to a landlord.
Low-Interest Student Loans: Borrowing responsibly to fund higher education or specialized professional training can significantly boost your lifetime earning potential and career mobility.
Business Loans: Capital secured to launch or expand a profitable business venture can generate enterprise value, cash flow, and long-term economic returns.
What Defines "Bad Debt"?
Bad debt involves borrowing money to purchase depreciating assets items that lose value rapidly the moment you acquire them or financing consumable goods and daily lifestyle expenses that provide zero long-term financial return.
Characteristics of Bad Debt:
High Interest Rates: Frequently features exorbitant annual percentage rates (APRs) that compound rapidly against you (e.g., credit cards, personal loans, payday advances).
Asset Depreciation: Tied to items that lose value immediately upon purchase (e.g., brand-new cars, luxury electronics, clothing).
Negative Cash Flow: Requires ongoing monthly servicing payments without generating any offsetting income.
Prime Examples of Bad Debt:
Credit Card Debt on Consumables: Carrying a rolling balance from dining out, vacations, or general lifestyle spending at 20% to 30% APR creates an insurmountable financial drag.
High-Interest Personal Loans for Vacations or Events: Funding temporary experiences with expensive borrowed money drains future income to pay for past enjoyment.
Auto Loans on Luxury Vehicles: While transportation is often a necessity, taking out an oversized, high-interest loan on a luxury car that depreciates by thousands of dollars the moment it leaves the lot is a classic wealth drain.
The Fine Line: When "Good Debt" Turns Bad
It is important to note that the classification of debt is not always black and white. Even traditionally "good" debt can become "bad" debt if mismanaged:
Overleveraging on Real Estate: Buying a home or investment property that stretches your monthly budget beyond its limits turns an asset into a financial trap if unexpected maintenance or vacancies occur.
Student Loan Excess: Borrowing excessive sums for a degree field with poor employment prospects or low starting salaries can saddle a graduate with monthly payments that outweigh their career earnings.
Affordability: Any loan regardless of its label becomes dangerous if the monthly debt service obligations compromise your ability to cover basic living expenses, build an emergency fund, or save for retirement.
Strategic Framework for Managing Debt
Managing your debt responsibly requires balancing leverage with caution:
Prioritize High-Interest Payoff: Aggressively tackle bad debt (like credit cards) first using the debt avalanche or snowball method to stop the drain of high compounding interest.
Evaluate Opportunity Cost: Compare the interest rate of a potential loan against what your cash could earn if invested elsewhere. If a low-rate mortgage allows you to invest excess cash at a higher historical return, holding that debt strategically can make sense.
Maintain a Safety Buffer: Never take on new debt without an established emergency fund and a reliable monthly budget to service obligations comfortably through unexpected career changes.