Life is inherently unpredictable. Whether it is an unexpected medical emergency, a sudden vehicle breakdown, an urgent home repair, or an abrupt job loss, financial disruptions have a way of arriving precisely when we least expect them. Without a reliable safety net, these surprise events can easily derail years of careful budgeting, forcing individuals into high-interest debt or severe financial distress. Building and maintaining a dedicated emergency fund stands as the single most important foundation of personal financial health. This comprehensive guide explores exactly what an emergency fund is, why it matters, how much you need to save, and actionable steps to build yours without feeling overwhelmed.
Understanding the True Purpose of an Emergency Fund
An emergency fund is a pool of liquid cash set aside exclusively for covering urgent, unexpected expenses. It is fundamentally different from short-term savings accounts earmarked for a vacation, a new gadget, holiday shopping, or a down payment on a car. Instead, it acts as your personal financial insurance policy.
When financial shockwaves hit, having cash readily accessible prevents you from resorting to high-interest credit cards, personal loans, or premature retirement account withdrawals. Relying on credit during a crisis introduces compounding interest burdens that can transform a temporary setback into a long-term financial crisis. A robust cash cushion provides psychological peace of mind, empowering you to navigate life's uncertainties with confidence and stability.
How Much Should You Actually Save?
One of the most common questions individuals ask is how much money they need to stash away. While the traditional rule of thumb suggests saving three to six months' worth of essential living expenses, the exact target varies depending on your unique life circumstances, job stability, and household structure.
1. The Baseline Goal: Three Months of Living Expenses
For single earners with stable, salaried positions, dual-income households where both partners work, or individuals with low fixed monthly overhead, a three-month fund is often a solid starting milestone. This amount covers fundamental survival costs housing, utilities, groceries, insurance, and minimum debt payments if income temporarily ceases or dips.
2. The Standard Recommendation: Six Months of Living Expenses
Financial advisors widely recommend aiming for a full six months of essential expenses for most households. This window provides adequate breathing room to weather a prolonged job search, handle an extended medical recovery, or manage major home infrastructure failures.
3. When to Target Nine to Twelve Months
Certain situations call for a more conservative and robust cash cushion:
Freelancers and Self-Employed Individuals: Variable income streams, fluctuating client contracts, and the absence of employer-provided benefits mean independent workers should lean toward nine to twelve months of savings.
Single-Income Households: If your household relies entirely on one income earner to support dependents, a larger reserve protects against sudden employment termination.
Specialized Health Needs: Individuals managing chronic medical conditions or high-deductible insurance plans benefit from bolstering their cash reserves to cover maximum out-of-pocket medical limits.
Calculating Your Essential Monthly Expenses
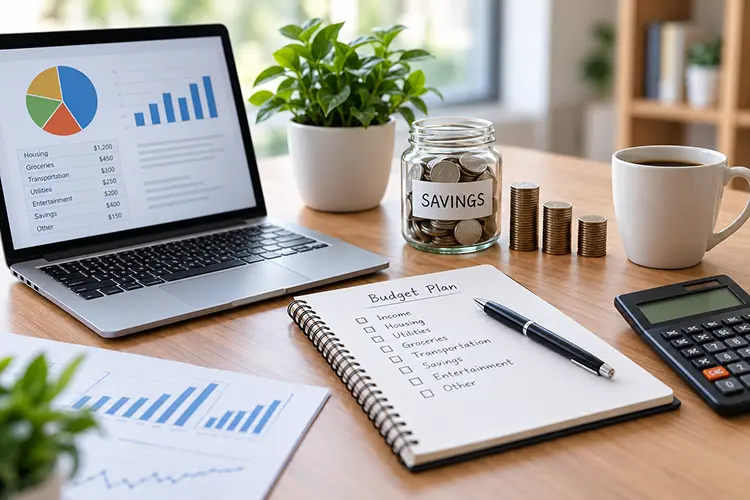
To determine your target savings number, you must calculate your essential monthly expenses not your total spending. Differentiating between mandatory survival costs and discretionary lifestyle choices ensures your savings target is both realistic and accurate.
Housing Costs: Rent or mortgage payments, property taxes, and home insurance.
Utilities and Communication: Electricity, water, gas, internet, and basic phone service.
Groceries and Sustenance: Essential supermarket food purchases (excluding dining out and entertainment).
Transportation: Public transit passes or car payments, auto insurance, and basic fuel required for commuting to work.
Healthcare: Health insurance premiums, essential prescription medications, and regular medical upkeep.
Debt Obligations: Minimum required payments on existing loans or credit lines to protect your credit score during a crisis.
Once you sum these baseline categories, multiply the total by your target number of months (3, 6, or 12) to establish your ultimate emergency fund goal.
Where Should You Keep Your Emergency Cash?
An emergency fund must balance two competing priorities: liquidity (instant accessibility) and safety (protection from market volatility). Because emergencies strike without warning, your cash cannot be tied up in volatile investments like stocks, cryptocurrency, or long-term certificates of deposit that carry early withdrawal penalties.
High-Yield Savings Accounts (HYSAs): Currently the premier option for storing emergency reserves. HYSAs offer competitive interest rates that outpace traditional brick-and-mortar savings accounts while keeping your money fully liquid and FDIC-insured.
Money Market Accounts: Another viable vehicle providing easy access via debit cards or check-writing privileges while earning respectable interest yields.
Checking Account Buffers: While some cash should sit in your primary checking account for immediate utility drafts, keeping the bulk of your emergency fund in a separate, dedicated online savings account prevents accidental spending.
Step-by-Step Strategy to Build Your Fund
Accumulating thousands of dollars in cash can feel intimidating, but breaking the process down into manageable, systematic steps makes the goal entirely achievable.
Start With a Mini-Emergency Milestone: Before tackling a full three-to-six-month fund, aim for an initial starter buffer of $1,000. This smaller milestone catches minor shocks like a flat tire or a sudden appliance repair without requiring credit card debt.
Automate Your Savings: Treat your emergency fund like a non-negotiable monthly bill. Set up automatic transfers from your primary checking account to your high-yield savings account on payday. Even transferring $25 or $50 per week builds significant momentum over time.
Redirect Windfalls: Fast-track your progress by channeling unexpected financial inflows straight into your reserve. Tax refunds, work bonuses, monetary gifts, or profits from selling unused household items can instantly supercharge your savings balance.
Audit and Adjust Annually: Your financial life evolves over time. Whenever you experience major life transitions such as moving to a new city, buying a home, changing careers, or welcoming a child recalculate your monthly baseline expenses and adjust your emergency fund target accordingly.
Conclusion
Building an emergency fund is a journey of financial self-care and resilience. By calculating your essential monthly expenses, setting a realistic savings target, and utilizing a high-yield savings account, you insulate yourself against life's unexpected turns. Taking control of your cash reserves today ensures that when unexpected expenses arise tomorrow, you can face them with absolute financial peace of mind.