Managing your money effectively is the single most powerful step you can take toward achieving financial freedom. Yet, for many people, the word "budget" evokes feelings of restriction, frustration, and tedious paperwork. It feels like a financial diet that dictates what you cannot do rather than a plan that empowers you to achieve what you truly want.
In reality, a well-constructed budget is not about deprivation; it is a spending plan designed to give you absolute control over your hard-earned cash. By telling your money where to go instead of wondering where it went, you can eliminate financial stress, fund your passions, and build lasting wealth. Here is a comprehensive, step-by-step guide on how to create a realistic budget that actually works for your lifestyle.
Step 1: Calculate Your Total Net Monthly Income
The foundation of any successful budget is an accurate understanding of your cash flow. Before you can assign dollars to different categories, you must know exactly how much money enters your household each month.
Focus on Net Income: Always base your budget on your net income (take-home pay) rather than your gross salary. Your net income is what remains after taxes, social security, health insurance premiums, and retirement contributions are deducted from your paycheck.
Account for Variable Income: If you are a freelancer, contractor, or earn commission-based wages, calculate your average monthly take-home pay over the past six to twelve months. Always build your baseline budget around your lowest earning month to maintain a safe financial cushion.
Include Side Hustles: Factor in predictable secondary income streams, rental income, or regular investment dividends only after confirming they consistently hit your account.
Step 2: Track and Categorize Your Spending Habits
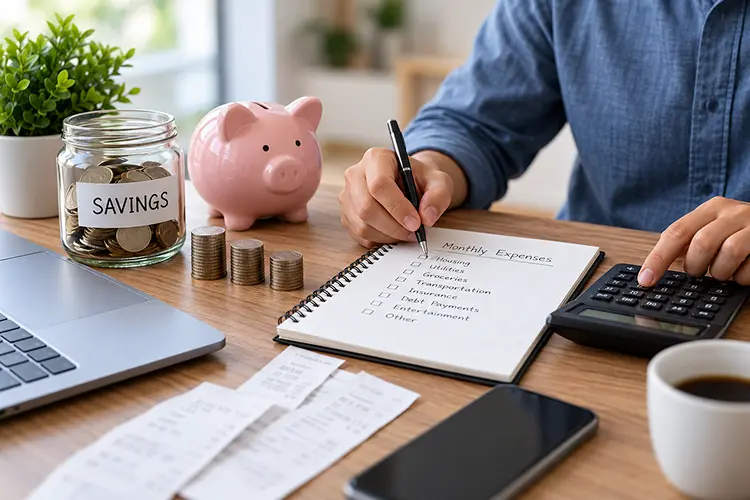
Before building a new spending plan, you need to understand where your money currently flows. Review your bank statements, credit card bills, and digital payment apps for the past 60 to 90 days.
As you review your purchases, divide them into two primary buckets: fixed expenses and variable expenses.
Fixed Expenses: These are predictable, recurring bills that remain relatively constant month after month. Examples include rent or mortgage payments, auto insurance, loan payments, and subscription services.
Variable Expenses: These fluctuate based on your choices and lifestyle habits. Examples include groceries, dining out, entertainment, utility bills, clothing, and impulse shopping.
Spotting spending leaks during this phase is crucial. You might discover that minor daily expenses such as specialty coffee runs, convenience store snacks, or unused digital memberships are quietly consuming hundreds of dollars each month.
Step 3: Choose a Budgeting Framework That Fits You
There is no single "correct" way to budget. The best financial system is the one you can maintain consistently over the long term. Here are three popular and effective budgeting frameworks to consider:
1. The 50/30/20 Rule
Popularized by Elizabeth Warren, this method divides your after-tax income into three distinct buckets:
50% for Needs: Essential living expenses required for survival, including housing, utilities, basic groceries, minimum debt payments, and healthcare.
30% for Wants: Lifestyle choices and discretionary spending, such as dining out, hobbies, vacations, and entertainment.
20% for Savings and Debt Payoff: Allocations toward building an emergency fund, retirement accounts, or paying down high-interest credit card debt beyond the minimums.
2. Zero-Based Budgeting
In a zero-based budget, your total income minus your total expenses must equal zero. Every single dollar you earn is assigned a specific job whether that is paying rent, buying groceries, investing, or saving before the month begins. This method ensures no money slips away unmonitored.
3. The Envelope System
A classic cash-based approach where you withdraw physical money for variable spending categories (like groceries, entertainment, and dining out) and place them into labeled physical envelopes. Once an envelope's cash is gone, discretionary spending for that category stops until the next month.
Step 4: Set Clear Financial Goals
A budget without goals lacks purpose. When you give your money specific targets to work toward, staying disciplined becomes much easier.
Short-Term Goals: Objectives you want to accomplish within the next year, such as paying off a credit card, building a $1,000 starter emergency fund, or saving for an upcoming holiday trip.
Medium-Term Goals: Milestones spanning one to five years, such as saving for a home down payment, purchasing a reliable vehicle, or clearing student loan debt.
Long-Term Goals: Future milestones like funding retirement, achieving financial independence, or buying property.
Aligning your monthly budget contributions directly with these milestones transforms budgeting from a chore into a rewarding roadmap for your future.
Step 5: Monitor, Review, and Adjust Regularly
Creating a budget is not a one-time event; it is an ongoing practice. Your first month's budget will rarely be perfect, and unexpected expenses will always arise.
Weekly Check-Ins: Spend ten minutes once a week reviewing your spending against your budget targets. This prevents nasty surprises at the end of the month.
Embrace Flexibility: If you overspend in one category like dining out adjust by trimming another flexible category like entertainment later in the month.
Update as Life Changes: Whenever you experience a lifestyle shift, such as receiving a raise, moving to a new apartment, or changing jobs, revisit your budget to ensure your allocations reflect your current reality.
Conclusion
Creating a budget is an empowering act of financial self-care. By calculating your net income, tracking your spending, choosing a framework that matches your personality, and setting clear goals, you take complete control of your financial destiny. Start small, stay consistent, and watch how a structured spending plan transforms your relationship with money.