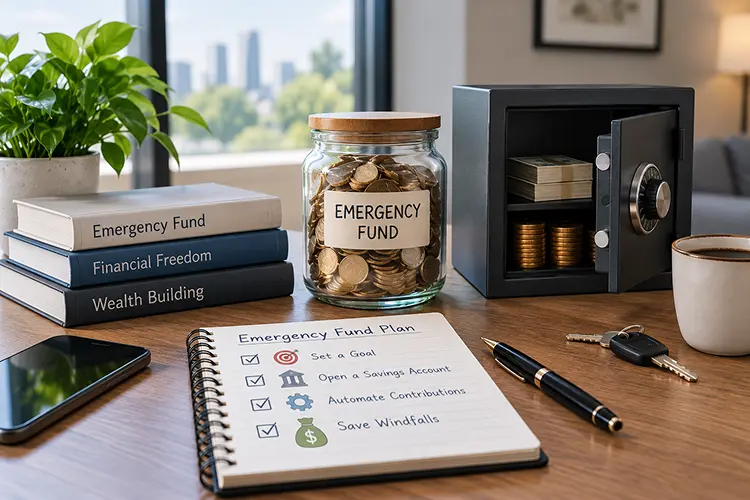
Building an emergency fund is the single most important step you can take to secure your financial future. Without cash reserves, unexpected expenses—such as a medical emergency, car breakdown, or sudden job loss—can easily force you into high-interest debt.
Here is a practical, step-by-step framework to help you calculate your target, open the right account, and build your financial safety net systematically.
Step 1: Calculate Your Target Savings Goal
Before setting aside money, you need to determine how much you actually need to save. As outlined in our Emergency Fund Guide, your target depends on your monthly essential living expenses (housing, utilities, groceries, transportation, and minimum debt payments).
The Starter Goal: Aim for an initial milestone of $1,000 to handle minor shocks like appliance repairs or urgent medical copays without relying on credit cards.
The Core Target: Build toward 3 to 6 months of essential living expenses if you have a stable, salaried position.
The Conservative Target: Aim for 9 to 12 months of expenses if you are self-employed, work on commission, operate as a single-income household, or support dependents.
Step 2: Choose the Right Place to Store Your Cash
An emergency fund must be kept separate from your daily checking account to prevent accidental spending, but it must remain instantly accessible in a crisis.
High-Yield Savings Accounts (HYSAs): The ideal vehicle for your emergency cash. HYSAs offer competitive interest rates that outpace traditional brick-and-mortar banks while keeping your money fully liquid and FDIC-insured.
Avoid Risky Assets: Never invest your emergency fund in stocks, cryptocurrency, or long-term certificates of deposit (CDs) that lock up your cash or expose you to market volatility.
Step 3: Automate Your Contributions
Relying on willpower alone to save money often leads to inconsistent results. Automation is the secret weapon of consistent savers.
Set Up Automatic Transfers: Schedule a recurring transfer from your checking account to your high-yield savings account on every payday.
Start Small and Scale Up: If saving 10% or 20% of your paycheck feels impossible right now, start with $25 or $50 per week. Once that feels comfortable, increase your transfer by 1% each month.
Step 4: Fast-Track Your Savings with Windfalls
Supercharge your progress by channeling unexpected financial inflows straight into your reserve rather than spending them on lifestyle upgrades.
Redirect Bonus Cash: Send tax refunds, work bonuses, monetary gifts, or profits from selling unused items directly to your emergency savings account.
Cut Temporary Expenses: Temporarily trim flexible categories—such as dining out or entertainment—for a few months to accelerate your journey toward your 3-month milestone.