One of the most common questions in personal finance is, "How much money should I actually be saving?" While the answer depends heavily on your personal income, living costs, and life goals, financial experts generally agree on a few proven baseline frameworks to help you find your target.
Without a clear savings target, it is easy to let lifestyle inflation swallow up your earnings, leaving you vulnerable to unexpected financial shocks. Here is a practical guide to calculating how much you should save, divided into clear milestones for emergencies, short-term goals, and long-term wealth building.
Step 1: The Emergency Fund Target (Your Financial Safety Net)
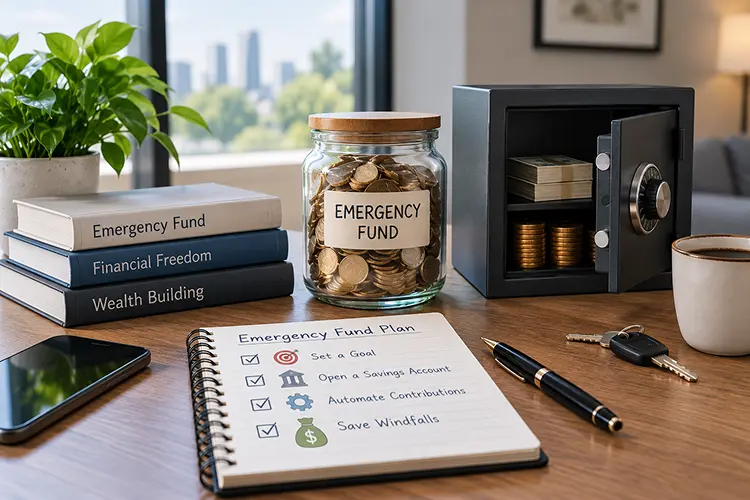
Before focusing on long-term investments or discretionary savings, your immediate priority should be establishing an emergency fund. As explored in our Emergency Fund Guide, this money protects you against sudden job loss, medical emergencies, or urgent repairs.
The Baseline Goal: Aim for 3 to 6 months of essential living expenses (housing, utilities, groceries, insurance, and minimum debt payments).
Who Needs 6+ Months? If you are self-employed, work in a volatile industry, operate as a single-income household, or support dependents, aim closer to 9 to 12 months of expenses to ensure maximum financial security.
Step 2: The 50/30/20 Rule for Monthly Savings
If you are looking for a straightforward monthly percentage to guide your paycheck allocations, the 50/30/20 rule is one of the most reliable budgeting frameworks available. It divides your net (take-home) income into three distinct buckets:
50% for Needs: Fixed and essential living costs required for daily survival (rent/mortgage, utilities, basic groceries, healthcare, and minimum loan payments).
30% for Wants: Lifestyle choices, dining out, hobbies, entertainment, and vacations.
20% for Savings and Debt Payoff: Direct allocations toward building your emergency fund, retirement accounts, and paying down high-interest debt beyond the minimum requirements.
Under this model, dedicating 20% of your take-home pay to savings and wealth building serves as the gold standard for long-term financial health.
Step 3: Age-Based Long-Term Retirement Benchmarks
Beyond your monthly cash savings and emergency reserves, tracking your cumulative retirement savings against your age ensures you are on pace for long-term independence. Financial planners often use salary-multiplier benchmarks to measure retirement progress:
By Age 30: Aim to have saved the equivalent of 1x your annual salary.
By Age 40: Aim for 3x your annual salary.
By Age 50: Aim for 6x your annual salary.
By Age 60: Aim for 8x to 10x your annual salary.
Note: These benchmarks are general guidelines and can be adjusted based on when you plan to retire and your projected retirement lifestyle expenses.
Actionable Plan to Hit Your Savings Goals
If saving 20% of your income or reaching these milestones feels overwhelming right now, start small and scale up progressively:
Automate Your Transfers: Set up automatic deposits from your checking account to a high-yield savings account on payday. Even starting with 5% of your income builds immediate momentum.
Increase Savings by 1% Each Quarter: If you currently save 5%, bump it to 6% in three months, and continue scaling upward until you reach your target percentage.
Channel Windfalls Directly Into Savings: Direct tax refunds, work bonuses, or monetary gifts straight into your savings or emergency fund rather than spending them on lifestyle upgrades.